Preparing for retirement can feel difficult when you are unsure how much money you will need or whether your current savings will be enough. Everyday expenses, rising living costs, debt payments, and family responsibilities can make it challenging to set aside money for the future. Without a clear strategy, you may continue saving without knowing whether you are moving toward your retirement goals.
The good news is that you can improve your retirement outlook by reviewing your finances, understanding your workplace retirement benefits, and making informed decisions about savings and investments.
Retirement Planning services can help you organize these decisions into a practical strategy. When combined with a well-managed 401(k) retirement plan, a clear approach can help you identify potential shortfalls, prepare for future expenses, and make better use of your available resources.
Understand How Much Money You May Need in Retirement
One of the first challenges in retirement preparation is estimating future expenses. Your financial needs after leaving full-time work may differ from your current budget, but some costs may remain the same or increase.
Housing, food, utilities, insurance, healthcare, transportation, and taxes can continue to affect your finances. You may also want money for travel, hobbies, family support, or other personal goals.
Start by reviewing your current spending and identifying expenses that may change when you retire. For example, commuting costs might decrease, while healthcare expenses could become more significant.
Next, estimate your expected retirement income. Depending on your circumstances, this may include:
- Withdrawals from retirement savings accounts
- Social Security benefits, if eligible
- Pension payments, if available
- Personal savings and investment income
- Part-time employment or other income sources
Comparing estimated expenses with expected income can reveal a potential shortfall. Finding that gap early gives you time to consider changes to your savings rate, retirement date, or spending expectations.
These estimates do not need to predict the future perfectly. Their purpose is to help you make decisions based on realistic assumptions rather than guesswork.
Make Your 401(k) Retirement Plan Work More Effectively
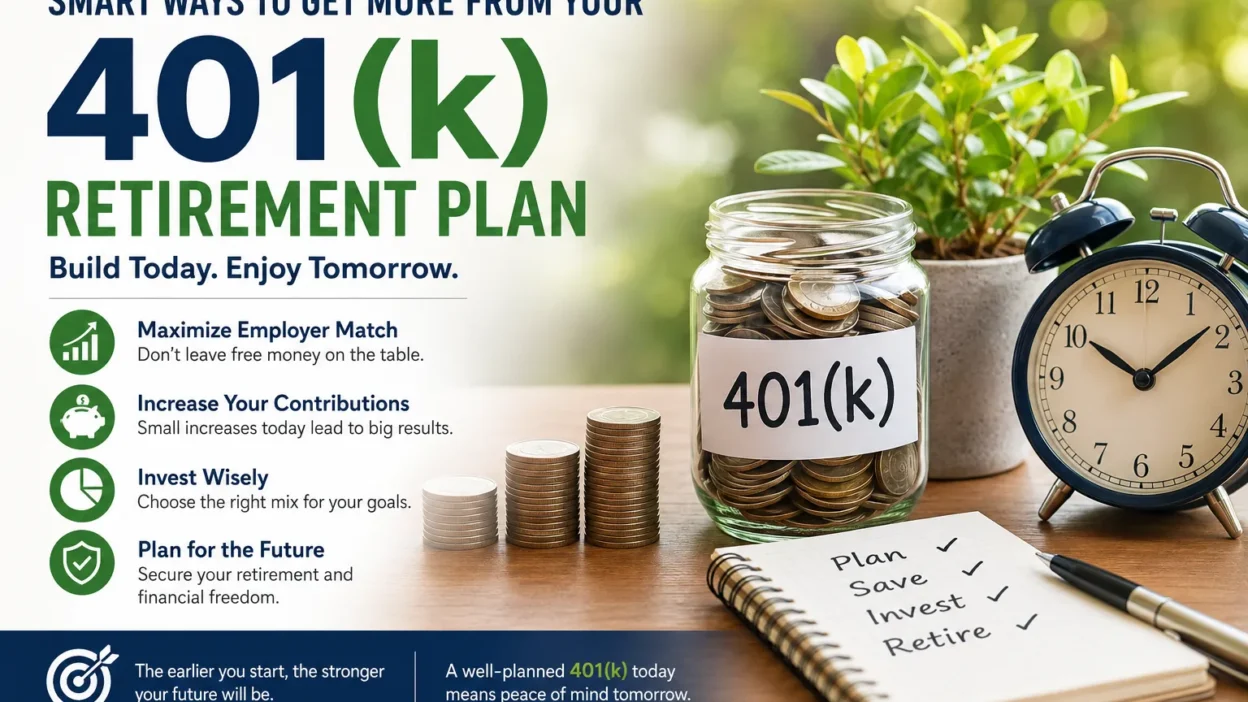
A 401(k) retirement plan allows eligible employees to save for retirement through payroll contributions. Depending on the plan, contributions may be made to a traditional account or a Roth account, each with different tax treatment.
Traditional 401(k) contributions are generally made before federal income taxes are calculated, while qualified Roth withdrawals are generally tax-free. Traditional account withdrawals are generally taxable, and the rules can vary based on the account and individual circumstances.
If your employer offers matching contributions, understand how the match works. Contributing enough to receive the full available match may help you build retirement savings more efficiently, provided doing so fits your budget and other financial priorities.
Review your contribution percentage regularly. If your income increases, consider whether you can raise your contributions without affecting essential expenses or emergency savings.
You should also understand the plan’s investment choices, fees, vesting schedule, and withdrawal restrictions. These details influence how your account operates and what options may be available when you change jobs or approach retirement.
Avoid Saving Without a Clear Target
Saving consistently is important, but contributions are more useful when they support a defined goal. Without a target, it can be difficult to know whether your current savings rate is appropriate.
Consider setting a retirement age range and estimating the amount of income you may need each year. Then review your current savings, expected contributions, and other potential income sources.
You can use retirement calculators to explore different scenarios. Try changing your contribution rate, expected retirement age, or estimated investment return to see how these assumptions affect the results.
Remember that projections are estimates, not guarantees. Investment returns fluctuate, inflation changes purchasing power, and your personal circumstances may evolve over time.
A useful approach is to review your progress at least annually. If your projected savings appear insufficient, you can consider increasing contributions gradually, reducing selected expenses, or adjusting your retirement timeline.
Choose Investments That Reflect Your Retirement Timeline
Investment decisions play an important role in retirement preparation. However, selecting investments based only on recent performance can lead to unnecessary risk.
Stocks may offer long-term growth potential but can experience significant declines. Bonds have different risk characteristics, and cash investments may provide greater short-term stability while potentially offering less growth over long periods.
Your investment allocation should reflect your time horizon, financial goals, other assets, and ability to tolerate losses.
Diversification can help spread risk across different investments, although it cannot prevent all losses. Some workplace plans also offer target-date funds that gradually adjust their investment mix as a selected retirement year approaches.
Before choosing a fund, review its fees, investment strategy, and risk level. Avoid assuming that an investment is suitable simply because it has performed well in the past.
If you are uncertain about your options, professional guidance can help you understand the trade-offs and choose an approach that fits your circumstances.
Prepare for Inflation and Unexpected Expenses
A retirement budget that works today may not cover the same expenses several years from now. Inflation can reduce the purchasing power of your savings, making it important to consider future costs when estimating your income needs.
Healthcare, housing, insurance, and everyday living expenses deserve particular attention. Your retirement plan should also account for costs that may be difficult to predict, such as home repairs or changes in family responsibilities.
Building an emergency fund can help you handle unexpected expenses without immediately withdrawing money from retirement accounts. The amount you need depends on your income stability, household expenses, and existing financial resources.
It is also worth reviewing your insurance coverage and outstanding debt. High-interest debt can reduce the amount available for saving, while inadequate insurance may leave you financially exposed to certain risks.
Preparing for uncertainty can help protect your retirement savings from avoidable disruptions.
Understand Taxes and Withdrawal Strategies Before Retiring
Building retirement savings is only one part of the process. You also need to consider how you will access that money when your regular employment income ends.
Withdrawals from traditional retirement accounts are generally subject to income tax. Qualified Roth withdrawals generally receive different tax treatment, and specific eligibility requirements apply. Early withdrawals may trigger additional taxes or penalties unless an exception applies.
Your withdrawal strategy can affect how long your savings last and how much income remains available after taxes.
Before retirement, review your expected income sources, account balances, and anticipated expenses. Consider how withdrawals from different accounts may affect your overall financial position.
Required minimum distribution rules may apply to certain retirement accounts once you reach the applicable age. The details depend on account type and other circumstances, so check current rules before making decisions.
A qualified tax professional or financial adviser can help you evaluate your options and understand the potential consequences of major withdrawals or account transfers.
When Retirement Planning Services May Be Helpful
Managing retirement savings independently may work for some people, but coordinating several financial decisions can become complicated. You may need to balance investment choices, taxes, debt, retirement income, insurance, and family responsibilities.
Professional retirement guidance can help you organize these concerns and develop a plan based on your specific circumstances.
When evaluating a provider, ask what services are included, how fees are calculated, and how often your plan will be reviewed. Look for clear explanations rather than promises of guaranteed investment results.
A professional may help you estimate retirement expenses, evaluate your savings progress, compare investment options, and identify possible gaps. If your situation involves tax or estate planning questions, ask whether those services are provided directly or coordinated with other qualified professionals.
The goal is not to eliminate every uncertainty. It is to understand your options and make informed decisions as your needs change.
Review Your Retirement Strategy Every Year
Retirement preparation is an ongoing process. Your plan may need adjustments after a salary increase, job change, major purchase, marriage, or other important life event.
Set aside time each year to review your contribution rate, account balance, investment allocation, fees, and expected retirement date. Check whether your savings remain aligned with your goals and whether your anticipated income can cover future expenses.
If your circumstances have changed, update your assumptions rather than relying on an outdated plan. Small adjustments made consistently can be easier to manage than major changes made shortly before retirement.
You should also keep important account information organized, including beneficiary designations and plan documents. Reviewing these details periodically helps ensure your retirement arrangements remain consistent with your intentions.
Conclusion
A more secure retirement begins with understanding your financial needs and identifying the steps required to meet them. Estimating future expenses, contributing consistently, reviewing investment choices, and preparing for taxes can help you manage your savings more effectively.
A 401(k) retirement plan can provide an important foundation, but it works best as part of a broader strategy that considers your income, spending, investments, and future lifestyle.
Retirement Planning services may help you identify savings gaps and develop a realistic plan for addressing them. Start by reviewing your current contributions, checking your employer’s matching policy, and estimating your future expenses. With regular reviews and informed decisions, you can build a clearer path toward your long-term retirement goals.