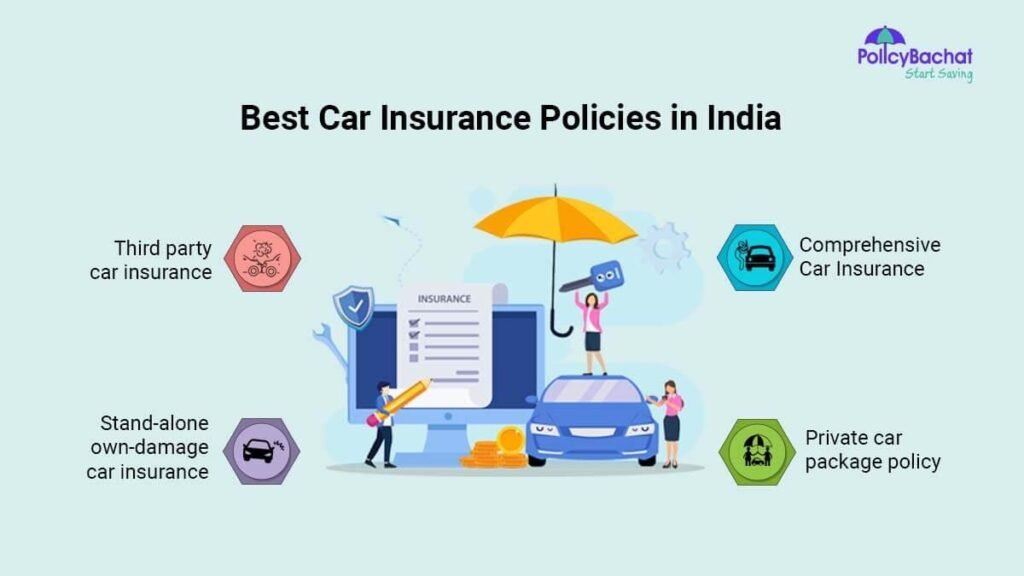
Published rankings of the best auto insurance company in india are a reasonable starting point and a poor final answer, because they rank on criteria that may not match what matters for your specific vehicle, city and usage. Building your own comparison framework, and running your current policy through it, tells you more than any general ranking can.
Why General Rankings Fall Short
Most public rankings weigh a handful of visible metrics: claim settlement ratio, premium competitiveness, and sometimes customer satisfaction surveys. When researching the best auto insurance company in India, these can be useful inputs, but they are aggregated at a national level, and insurance experience varies substantially by city, vehicle category, and claim type.
An insurer ranked highly nationally may have limited garage presence in your specific city. One with an average national settlement ratio may perform considerably better on the specific claim type—such as theft—that concerns you most given your parking situation.
Building a Framework That Fits Your Situation
Four factors, weighted according to your own circumstances, produce a more useful comparison than any generic ranking.
Claim settlement ratio across the last three years, weighted more heavily if you have a claims history or drive in a high-risk environment. Network garage presence specifically in your city, which matters more if you would use cashless settlement than if you are comfortable paying and claiming reimbursement. Add-on terms relevant to your vehicle’s age and your location, zero depreciation for a new car, engine protection in a flood-prone city. And declared value offered at a normalised comparison point, since this determines your payout ceiling on the claims that matter most.
Weight these according to what actually applies to you rather than treating all four equally by default.
Running Your Current Policy Through the Framework
Before comparing alternatives, evaluate what you already hold. Check your insurer’s settlement ratio trend over the last three years. Confirm your city’s garage network is genuinely adequate rather than assumed adequate. Review your actual add-ons against your vehicle’s current age, since add-ons chosen years ago may no longer suit an ageing vehicle. And check your current declared value against an independently calculated baseline.
This step is frequently skipped, and it should not be. Many owners compare alternatives against an idealised version of their current policy rather than its actual, current state, which biases the comparison toward switching even when the existing policy, properly optimised, would serve just as well.
What a Fair Comparison Looks Like
Once you understand your current policy’s actual standing on the four factors, request quotes from two or three alternatives on identical terms: the same declared value, the same add-ons, the same deductible. This is the step most comparisons skip, comparing headline premiums across policies that differ substantially in what they actually offer.
A quote that looks cheaper while offering a lower declared value or thinner add-on terms is not a genuine alternative. It is a different, lesser product being compared on price alone.
When Switching Makes Sense
Switching is justified where an alternative offers a materially better declared value on equivalent terms, a demonstrably stronger settlement record over multiple years specifically in claim types relevant to you, or substantially better garage coverage where you actually drive.
Switching purely because a published ranking places another insurer higher, without verifying these specifics against your own situation, frequently trades a known quantity for an unknown one on the strength of a metric that may not even apply to your circumstances.
Where Bajaj Car Insurance Fits This Framework
Applying this method to car insurance policy options specifically means checking the same four factors rather than accepting general reputation: the settlement ratio trend, garage presence in your city, add-on terms matched to your vehicle’s age, and declared value normalised against competing quotes.
The Bottom Line
A general ranking tells you what performs well on average, nationally, across an undefined mix of claim types and cities. Your own comparison, run against your specific city, vehicle age and usage pattern, tells you what will actually serve you. The second is considerably more useful, and it takes perhaps thirty minutes longer to build.
Documenting Your Comparison
Keep a simple record of what you compared: the settlement ratios checked, the garage networks confirmed, and the declared values quoted by each insurer. If you decide to switch, this record is useful when explaining your No Claim Bonus history to the new insurer, and if you decide to stay, it gives you a documented basis for that decision at your next renewal rather than starting the comparison from scratch each year.
Revisiting the Comparison Periodically
Insurer performance is not static. A settlement ratio trend worth checking this year may look different in two years, and garage networks expand or contract as insurers adjust their partnerships. Rerunning this comparison every two to three years, rather than once and never again, keeps your policy aligned with which insurer is actually performing well currently rather than which one was strongest when you first compared.